Alphabet Inc., the parent company of Google, faced a turbulent reception on Wall Street following the release of its third-quarter financial results. Despite delivering a headline-grabbing performance in its cloud computing division, the tech giant saw its market capitalization evaporate by more than $280 billion as investors reacted sharply to decelerating growth in its core search business and massive capital expenditures dedicated to the artificial intelligence arms race. The after-hours sell-off, which saw the stock price tumble by more than 11%, underscores a growing investor anxiety regarding the transition from traditional search-based revenue models to the capital-intensive world of generative AI.
The Cloud Success Story
The primary bright spot in Alphabet’s latest earnings report was undeniably Google Cloud. The division reported a monumental surge in revenue, which more than doubled to reach $30.7 billion for the quarter. This performance provided a crucial buffer for a company otherwise grappling with cooling interest in its traditional advertising platforms. Perhaps most impressively, the Cloud division’s profit margins expanded to 36.2%, silencing skeptics who had argued in previous quarters that the business unit had hit a ceiling regarding profitability.
For analysts like Dan Ives of Yorkville Ives equity research, the cloud results represent the "print we have been waiting for." Ives maintains a bullish outlook, suggesting that the massive scale of Google Cloud’s success is a more significant indicator of the company’s long-term health than the "lighter" numbers in the search division that dominated investor sentiment during the trading session. However, the market’s immediate reaction suggested that institutional investors were less interested in the long-term potential of Cloud and more focused on the immediate stagnation of the company’s cash cow: Google Search.
The Search Stagnation and AI Cannibalization
Google Search remains the bedrock of Alphabet’s empire, yet its recent performance has raised red flags. In the third quarter, Search revenue grew by 12% to $63.4 billion. While this figure remains substantial, it represents a significant deceleration from the 17% growth observed in the second quarter and the 19% growth recorded in the first quarter of the year. Most concerning to market observers was that the performance fell short of the 15% growth target that many analysts had baked into their models.
The broader fear circulating among analysts is the concept of "AI cannibalization." As Alphabet integrates generative AI features directly into the search experience, there is a mounting concern that the traditional advertising-heavy search model—where users click on sponsored links—is being disrupted by AI-generated summaries. If the search experience becomes too efficient at providing answers without requiring users to click through to external websites or ad-supported links, the primary engine of Alphabet’s profitability could face a structural decline. David Wagner, head of equity and portfolio manager at Aptus Capital Advisors, succinctly summarized the sentiment: "The problem is everything else." While Cloud performed its duty, the uncertainty surrounding the search franchise created a vacuum of confidence that no amount of cloud growth could fill.
Financial Overview and the Impact of Paper Losses
Alphabet reported total third-quarter revenue of $127.6 billion, representing a 25% increase year-over-year from $102.3 billion. While this result was largely in line with consensus estimates provided by S&P Global Visible Alpha, the bottom-line earnings told a different story. Earnings per share tumbled to $2.12 from $2.87 in the same period last year.
This earnings miss was largely attributed to an $8.7 billion paper loss on Alphabet’s equity investments, which alone trimmed 55 cents per share from the company’s bottom line. Much of this volatility is linked to Alphabet’s diverse portfolio of investments, including its stake in private entities like SpaceX. Analysts such as Luke Lango have labeled these losses as "accounting noise," arguing that they do not reflect the fundamental operational strength of the underlying businesses. Despite the EPS decline, operating income rose by 30% compared to the previous year, highlighting that the core business remains robust even if non-operating accounting factors weigh on the final reported figure.
The Capex Conundrum
Perhaps the most significant driver of investor apprehension is the unprecedented level of capital expenditure (capex). Alphabet reported $51.4 billion in capex for the quarter, a staggering increase from the $24 billion spent during the same period a year ago. This spending is part of a broader, industry-wide trend among hyperscalers—including Microsoft, Amazon, and Meta—who have collectively committed to spending upwards of $2 trillion over a two-year period to build out the infrastructure required for the AI revolution.
Alphabet confirmed that it expects its capital spending to remain elevated, forecasting that capex will reach $200 billion in 2026 and rise further to $300 billion in 2027. CFO Anat Ashkenazi has indicated that more granular details regarding this trajectory will be provided in the fourth quarter. The sheer scale of this investment has pushed Alphabet’s free cash flow into negative territory—recording a negative $9.1 billion for the quarter, compared to negative $5.9 billion in the second quarter.
As Luke Lango observed, the market is essentially punishing Alphabet for using shareholders’ capital to fund the transition to an AI-first future. It is a "how do we pay for it" problem rather than a "nobody wants it" problem, suggesting that the long-term utility of the infrastructure being built is not in doubt, but the short-term impact on shareholder dividends and stock buybacks is severe.
Chronology of the AI Pivot
To understand the current tension, one must look at the timeline of Alphabet’s aggressive pivot. In June, the tech giant successfully raised $84.8 billion in equity, a round that included a $10 billion investment from Warren Buffett’s Berkshire Hathaway. This capital injection was explicitly earmarked to accelerate the AI buildout. The third quarter results represent the first full financial reporting period since that capital raise, placing the company’s management team under intense scrutiny regarding how efficiently that money is being deployed.
The narrative of the past nine months has been defined by a relentless drive to secure GPU capacity and build massive data centers. While competitors have also increased their spending, Alphabet’s dual role as a cloud provider and a search engine operator makes its spending path more complex. The company must balance the need to innovate on the model-training side with the necessity of maintaining the performance of its consumer-facing search engine.
CEO Perspective and Future Outlook
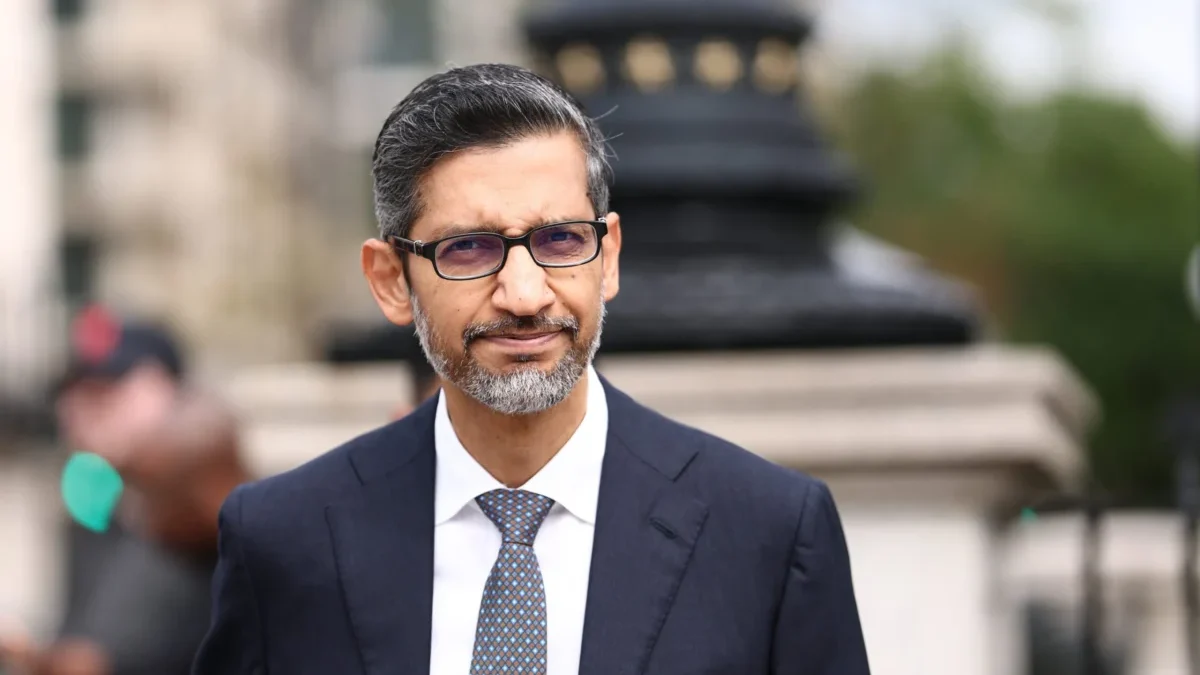
Despite the market’s negative reaction, Alphabet CEO Sundar Pichai maintained a tone of optimism, focusing on the broader "full-stack" capabilities of the organization. "We had a strong quarter and are now on a half-trillion-dollar revenue run rate," Pichai stated. He emphasized that the company’s deep integration of AI across its product ecosystem is driving momentum, citing the 25% year-over-year revenue growth as proof that the company is successfully scaling its operations.
The challenge for the executive team in the coming quarters will be to reconcile this "half-trillion-dollar" ambition with the reality of investor patience. The company is currently operating in a transition phase where the costs of building the future are being realized today, while the revenue benefits of that future remain partially theoretical.
Analytical Implications
The implications of the third-quarter earnings report are threefold. First, the success of Google Cloud proves that Alphabet can compete at the highest level of enterprise computing, potentially offsetting the cyclical nature of advertising revenue. Second, the "Search" problem is real and requires a sophisticated solution; the market will be looking for evidence that AI-driven search can be monetized as effectively as the traditional link-based model. Finally, the capital expenditure forecast for 2026 and 2027 sets a high bar for performance. If the $200 billion to $300 billion in spending does not yield a proportional increase in efficiency or new revenue streams, Alphabet could face sustained pressure from institutional shareholders.
As the tech sector continues to navigate the post-pandemic era and the onset of the AI age, Alphabet finds itself at a crossroads. The company is effectively betting its massive cash reserves on the idea that the infrastructure it is building today will define the next decade of internet interaction. While the market has responded with skepticism, the fundamental strength of a $127.6 billion revenue quarter suggests that Alphabet remains a dominant force in global technology. The path forward will likely be defined by the company’s ability to demonstrate that its massive AI investment is not just a cost center, but the engine of its next phase of growth.