When global oil prices breached the psychological barrier of $100 per barrel this week, the financial markets reacted with a surprising degree of stoicism. In previous decades, such a headline would have triggered immediate panic, reminiscent of the energy crises of the 1970s and 1980s that left motorists stranded in serpentine queues and sent inflation soaring. However, as Brent crude climbed to a high of nearly $110 per barrel on Monday—marking a 4% surge and its highest valuation since May—economists and market analysts are suggesting that the "oil shock" narrative has evolved significantly. While the numbers on the screen evoke historical trauma, the underlying mechanics of the modern U.S. economy suggest that the impact of triple-digit oil is far less systemic than it once was.
A Changing Economic Landscape
To understand why $100 oil is being met with a measured response rather than outright alarm, one must look at the shift in the American energy profile. The United States has transitioned from a position of chronic energy dependence to becoming a net energy exporter. This structural pivot means that while energy price volatility remains a burden for households, it simultaneously acts as a stimulus for domestic energy producers.
According to Michael Pearce, chief U.S. economist at Oxford Economics, the "shocks" of the past hit differently in the current era. "Higher oil prices represent a transfer of wealth," Pearce noted. "For households, it is an immediate tax on disposable income, but for the robust U.S. energy sector, it represents a significant revenue windfall that supports investment and regional employment."
Furthermore, the share of income that the average American household allocates to gasoline has plummeted. Historical data from JPMorgan illustrates this starkly: in 1980, amid global instability, Americans spent approximately 6% of their total income on gasoline. Today, that figure hovers around 2.5%. This reduction is due to a combination of improved vehicle fuel efficiency, shifting consumption habits, and the fact that wages have generally outpaced the growth of fuel costs over the long term.
The Diesel Dilemma and Supply Chain Pressures
While the crude oil price is a headline-grabber, experts argue that the true economic concern lies elsewhere: in the refined product market. The disconnect between crude prices and the price of gasoline and diesel is widening, largely due to a long-term shortage in global refinery capacity.
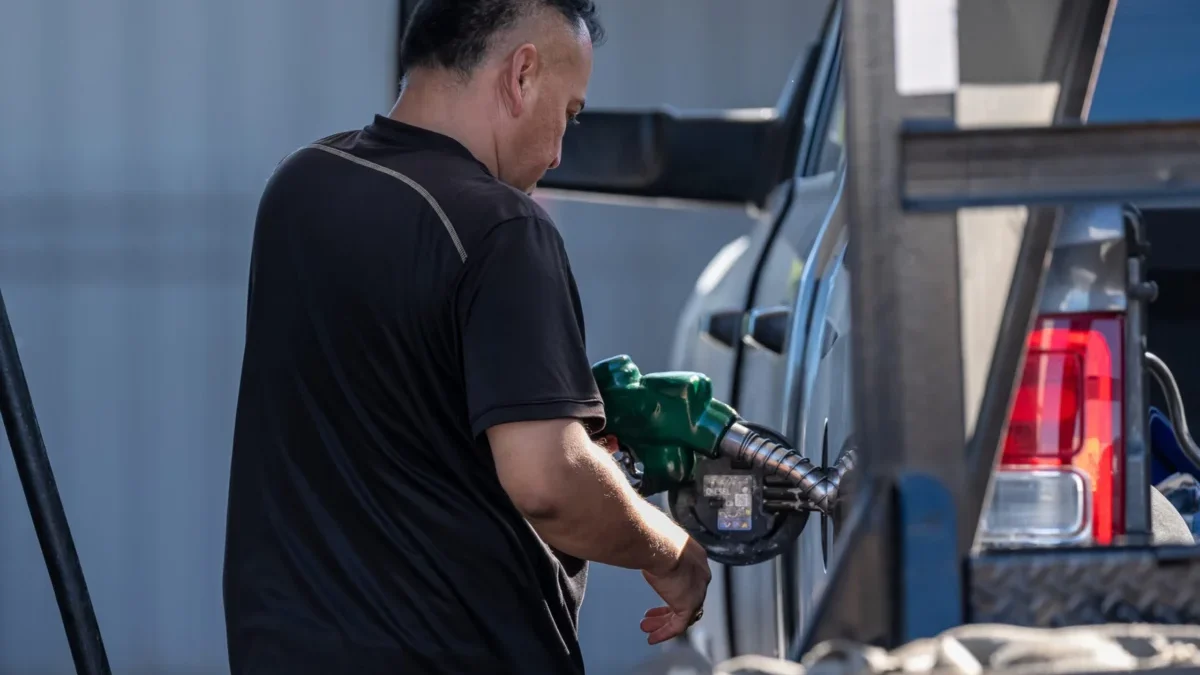
Refineries, the industrial facilities that transform raw crude into usable consumer products, have faced years of underinvestment and regulatory pressure to pivot toward cleaner energy sources. This has created a bottleneck. As diesel prices reached a record $6.39 per gallon—up significantly from the $3.70 seen a year prior—the impact is felt not just at the pump, but across the entire supply chain. Diesel is the lifeblood of the modern economy; it powers the heavy-duty trucks that transport goods, the tractors that harvest agricultural produce, and the industrial generators that keep factories humming.
If these elevated costs persist, the implications for consumer prices are clear. Unlike gasoline, which directly drains household savings, high diesel costs are "baked into" the price of every item shipped via truck or rail. From produce in the grocery store to raw materials for construction, the inflation caused by high diesel costs is indirect but pervasive.
Chronology of the Current Price Surge
The current volatility began earlier this month as geopolitical tensions, particularly surrounding the situation in Iran, began to threaten supply routes.
- September 10: Analysts noted a sharp escalation in energy concerns as reports suggested potential supply disruptions in the Middle East, pushing diesel and crude prices to new recent highs.
- September 14: Brent crude officially crossed the $100 threshold, reaching $110 before a slight market correction.
- September 15: Prices settled around $107, indicating that the market was testing the upper bounds of resistance without triggering a full-scale sell-off in equity markets.
This recent surge follows a period of relative stability, making the sudden spike particularly jarring for logistics managers and manufacturing firms that rely on predictable energy budgeting.
The Inflationary Threshold
Patrick De Haan, head of Petroleum Analysis at GasBuddy, emphasizes that we are currently dealing with a "re-indexing" of what constitutes an economic emergency. "If you look at the real, inflation-adjusted price of oil, $100 today does not carry the same weight it did in 2008 or 2011," De Haan explained. "Economically speaking, we might need to see oil push toward $200 before we encounter the kind of demand destruction and systemic economic contraction that we saw in previous energy shocks."
Despite this, the cumulative effect of rising costs remains a headwind for the U.S. economy. Oxford Economics estimates that if current price levels hold through the final quarter of the year, it could shave several tenths of a percentage point off consumer-spending growth in the coming year. This is not enough to induce a recession on its own, but it serves as a "friction" that slows the velocity of the economy.
Vulnerability and Inequality
A critical nuance in this analysis is that the burden of high fuel costs is not distributed equally. While the "average" American household might be able to absorb a 2.5% energy expenditure, lower-income families are significantly more exposed. These households allocate a larger proportion of their income to non-discretionary items, leaving little room for the price swings seen at the pump.
As JPMorgan analysts pointed out, when gas prices rise, low-income households are forced to make trade-offs between essential goods. This leads to a contraction in discretionary spending, which can ripple through the retail and service sectors. De Haan notes that while the current situation is manageable, the real test will come around the holidays. If fuel prices remain at these elevated levels through late November and December, the seasonal increase in travel and freight demand could create a "pressure cooker" environment for consumers already stretched thin by persistent inflation in other sectors.
The Path Forward
Ultimately, the consensus among economists is that there is no single "tipping point" for crude oil that will automatically trigger a recession. The U.S. economy has demonstrated a surprising degree of resilience, buoyed by domestic production and a shift away from oil-intensive industrial processes.
However, the current situation serves as a stark reminder of the global nature of energy markets. Geopolitical instability remains the single largest "wild card" in the economic outlook. As long as refinery capacity remains tight and geopolitical hotspots continue to threaten the flow of energy, prices will likely remain volatile.
For now, as De Haan suggests, the American economy will likely "grimace and bear it." The transition to a post-fossil fuel future continues to be the long-term solution, but in the interim, the economy is learning to live with a higher, more expensive baseline for energy. The primary risk remains not the price of the barrel itself, but the potential for these costs to become entrenched in the supply chain, creating a persistent, sticky inflation that complicates the central bank’s ability to stabilize the broader economy. With gas prices trending toward $4.43 a gallon nationally—a sharp increase from the $3.20 seen a year ago—the focus remains on whether these costs are a temporary spike or the start of a sustained period of high energy prices.