True financial competence is rarely the result of rigid spreadsheet management or extreme deprivation; rather, it is a byproduct of discerning the difference between conscious choice and unconscious habit. Over the past decade, financial analysts and consumer behaviorists have identified a recurring phenomenon: individuals who successfully accumulate wealth often share a common trait—a deliberate, evolving list of non-essential expenditures they have systematically eliminated. This process of “financial pruning” targets small, automated costs that, while seemingly insignificant individually, aggregate into substantial annual losses. By examining the lifecycle of household expenses, it becomes clear that the most effective path to capital preservation involves identifying the “autopilot” purchases that characterize modern consumer life.
The Mechanism of Invisible Spending
Consumer behavior research indicates that the modern household is subject to a phenomenon known as “subscription creep” and “convenience inflation.” As digital services, automated delivery, and retail environments optimize for frictionless spending, the psychological barrier to making small purchases has effectively vanished. Data from personal finance audits suggest that the average consumer underestimates their monthly “small-ticket” recurring expenses by approximately 25%. This discrepancy exists because these costs—ranging from streaming bundles and cloud storage to premium convenience markups—are often processed via autopay, removing the necessity of a conscious decision-making moment at the point of sale.
A Chronology of Consumption Shifts
The evolution of these spending patterns can be traced back to the late 2000s, coinciding with the rise of the “gig economy” and the expansion of direct-to-consumer subscription models. Prior to 2010, consumption was largely defined by tangible, one-time transactions. As the economy shifted toward service-based recurring models, the financial burden moved from capital expenditure to operational expenditure.
- The Rise of Convenience (2010–2015): The introduction of high-speed mobile internet and advanced logistics enabled the proliferation of on-demand services, such as meal delivery and grocery pre-processing.
- The Subscription Era (2015–2020): Media consumption pivoted from ownership to access. The bundling of digital services became the standard, masking the individual costs of content platforms.
- The Current Correction (2020–Present): Economic volatility and inflationary pressures have forced a re-evaluation of household budgets, leading a growing segment of the population to systematically dismantle these automated habits.
Categorizing Non-Essential Expenditures
To effectively manage a budget, financial experts suggest categorizing expenses based on their utility versus their markup.
The High-Margin Trap: Electronics and Warranties
Retailers frequently utilize extended warranties as a primary profit center. Analysis of consumer electronics shows that the failure rate for small devices—such as headphones or kitchen appliances—within the extended coverage window is statistically lower than the cost of the warranty itself. Financial advisors consistently note that self-insuring by maintaining a dedicated emergency fund is mathematically superior to purchasing third-party protection plans, which often carry profit margins exceeding 50%.
The Convenience Markup: Produce and Snacks
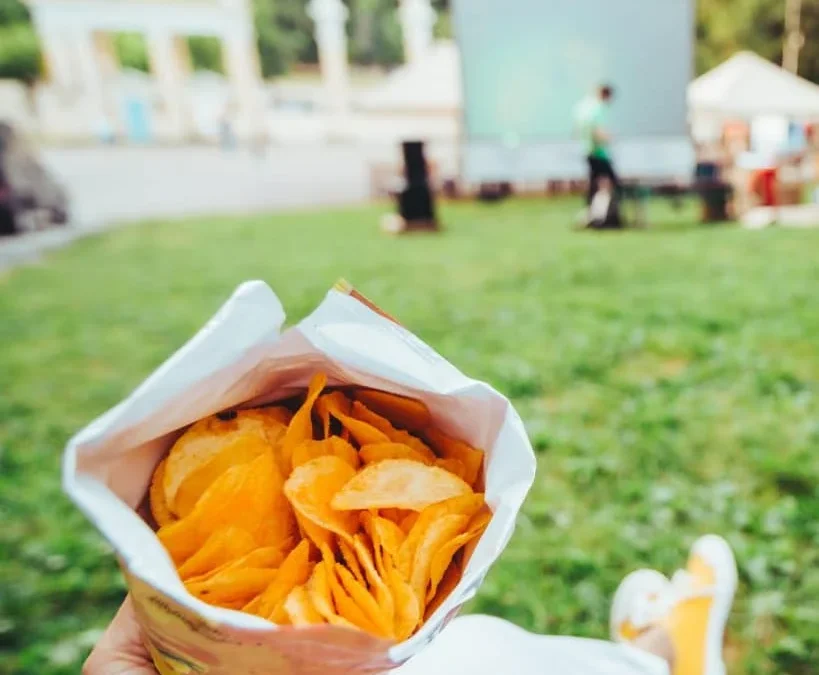
The “convenience tax” is most visible in the grocery sector. Pre-cut fruits and vegetables, as well as individually wrapped snack portions, often carry markups ranging from 30% to 300% compared to their raw, bulk counterparts. While proponents of these products cite time-saving benefits, the cumulative cost of these conveniences over a fiscal year often equates to a significant percentage of a household’s food budget.
The Generic Substitution Strategy
Pharmaceuticals and household cleaning supplies offer a clear-cut case study in marketing-driven inflation. According to FDA regulations, generic medications must contain the same active ingredients, strength, and dosage form as their brand-name counterparts. Despite this, brand-name versions frequently command a price premium of 20% to 50%. Similarly, household cleaning agents are often comprised of basic chemical compounds that are indistinguishable from store-brand alternatives, rendering the price difference purely a function of branding rather than performance.
Structural Adjustments for Long-Term Sustainability
The most significant financial impact often comes not from the elimination of daily coffee runs, but from larger, structural decisions regarding housing and recurring obligations.
Housing as the Primary Variable
Housing remains the largest expense for most households. The trend toward maximizing square footage—often driven by social signaling or speculative asset growth—frequently results in a “lifestyle inflation” trap. A larger home necessitates higher property taxes, increased utility consumption, higher maintenance costs, and larger furniture investments. Financial planners argue that housing should be viewed as a tool for utility rather than a status symbol. The implication is clear: every square foot of unused space incurs a continuous, unavoidable cost that compounds over the duration of ownership.
The Role of Recurring Charges
Subscription management has become a focal point for financial health. With the average consumer subscribing to multiple streaming services, software suites, and cloud storage plans, the total monthly output often exceeds the value derived from the services. Audits of personal bank statements reveal that a significant number of these accounts remain active despite minimal utilization. The recommendation from institutional financial advisors is to perform a quarterly “subscription audit,” canceling services that have not been utilized within a 30-day window.
Official Perspectives and Economic Implications
Economists from the Bureau of Economic Analysis (BEA) have noted that consumer spending behavior is a critical driver of the broader economy. However, from the perspective of individual financial stability, the shift toward a “frugality-by-design” mindset—defined by intention rather than deprivation—is viewed as a positive development for long-term household solvency.
Industry analysts observe that companies are increasingly responding to this shift. Retailers that offer “value-tier” private labels or bulk-purchasing options are seeing higher customer retention rates as consumers move away from premium-priced convenience. This market correction suggests that while consumer spending will continue, it is becoming increasingly polarized between essential value and high-end luxury, with the “middle-market” convenience sector under significant pressure to prove its value proposition.
Practical Implementation: A Roadmap for Financial Reorientation
For those seeking to optimize their personal balance sheet, the process should be sequential:
- Audit: Begin by reviewing the last three months of bank and credit card statements. Identify every recurring payment.
- Prioritize: Distinguish between essential services (utilities, insurance) and discretionary ones (streaming, subscriptions).
- Optimize: Replace name-brand consumables with generic alternatives. Transition from pre-processed goods to whole, bulk items.
- Maintenance: Establish a “maintenance fund” for repairs rather than purchasing extended warranties.
- Evaluate: Before any major purchase, particularly in housing or transportation, assess the long-term, non-obvious costs (taxes, insurance, maintenance) rather than just the upfront price.
Conclusion: The Philosophy of Intentional Spending
The objective of this financial realignment is not to suggest that individuals should eliminate all luxuries or comforts. Rather, it is to highlight the pervasive nature of unconscious spending. When a purchase is made out of habit, it lacks utility; when it is made out of intent, it serves a purpose. By systematically removing the friction of automatic, low-value spending, households can recapture capital that is better deployed toward long-term goals such as retirement savings, debt reduction, or investment in appreciating assets.
Ultimately, the distinction between those who effectively manage their finances and those who struggle is not a matter of income level, but a matter of discipline. The most successful individuals are those who have stopped buying things they do not need, thereby creating the financial headroom necessary to pursue the things that genuinely matter. Through the disciplined application of these principles, the average household can achieve a state of financial autonomy that is sustainable, resilient, and immune to the volatility of market-driven consumer trends.