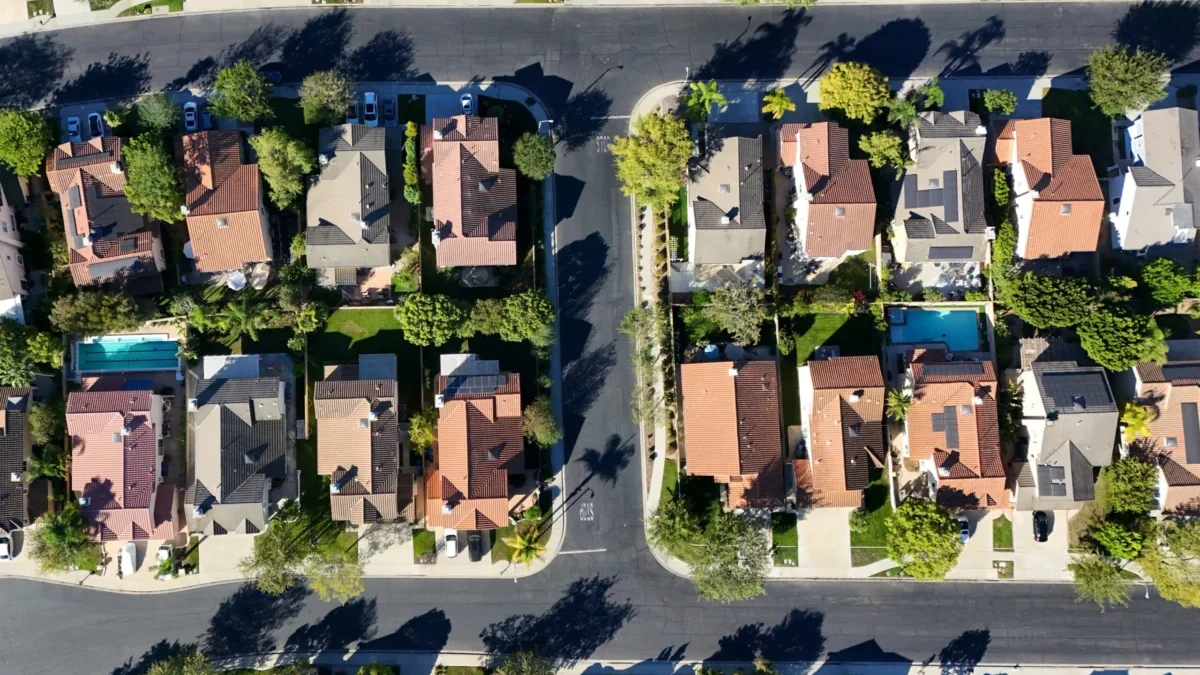
The national housing landscape is undergoing a profound recalibration as mortgage rates climb toward levels not seen since early 2025. With the 30-year fixed mortgage rate hitting 7.24% last week and the Freddie Mac weekly average settling at 6.95%, prospective homeowners are facing a volatile financial environment. This surge is not an isolated event but rather the latest manifestation of a broader economic struggle characterized by persistent inflation, aggressive Federal Reserve interest rate hikes, and an inventory-constrained market that refuses to yield to standard economic pressures.
For the average American household, these figures translate into a significant increase in monthly debt obligations. As borrowing costs escalate, the financial barrier to entry for homeownership is becoming increasingly insurmountable, forcing a shift in how buyers and sellers interact within a cooling market.
A Chronology of Economic Tightening
To understand the current impasse, one must look at the sequence of events that has defined the last 18 months of the real estate sector. Following the inflationary spike of late 2024 and early 2025, the Federal Reserve adopted a hawkish stance, prioritizing the suppression of the Consumer Price Index (CPI) over the immediate stability of the housing market.
By mid-2025, the Fed began a series of interest rate hikes intended to dampen aggregate demand. These moves were reflected almost immediately in the bond market, where the yield on the 10-year Treasury note—the benchmark against which 30-year mortgage rates are priced—began a steady ascent. By January 2025, rates were already elevated; however, the recent uptick in September 2026 suggests that the market has yet to find a ceiling. Industry analysts point to the September 16, 2026, policy updates from the Federal Reserve as a critical inflection point, signaling that borrowing costs will likely remain elevated for the foreseeable future to counter structural inflation.
The Erosion of Affordability
The impact of these rates is best measured in the monthly mortgage payment. According to Brett Johnson, a Colorado-based real estate professional, the math has become unforgiving. "For a significant portion of the buyer pool, the jump in interest rates effectively subtracts tens of thousands of dollars from their total purchasing power," Johnson noted. "A house that was within reach three months ago is now functionally overpriced, pushing families toward smaller properties, further commutes, or the decision to remain in the rental market indefinitely."
This sentiment is echoed by institutional data. The Mortgage Bankers Association (MBA) reported that mortgage applications for home purchases plummeted by 19% year-over-year for the week ending September 11, 2026. This data point is a leading indicator of a broader withdrawal from the market. When coupled with the fact that Google searches for "homes for sale" have declined by 15% compared to the previous year, it becomes clear that the psychological threshold for many consumers has been breached.
The Stagnation of Sales Volume
The decline in interest is not merely anecdotal; it is reflected in the cooling of completed transactions. Pending home sales—an indicator of future closed sales—fell to their lowest level in nearly three years during the four-week period ending September 13, 2026, marking a 5.4% year-over-year contraction.
The National Association of Realtors (NAR) has corroborated this downward trend, reporting that existing home sales dropped by 2% in August 2026. Most notably, the annual sales pace has dipped below the 4 million mark for the first time since June 2025. This stagnation creates a "frozen market" scenario: potential sellers, who are currently locked into historically low mortgage rates from years prior, are unwilling to list their homes and trade a 3% rate for a 7% rate. Consequently, the supply of available inventory remains constrained, preventing the market from achieving the equilibrium that typically follows a drop in demand.
Pricing Resilience and the Geography of Disparity
One of the most paradoxical features of the current housing market is that, despite the cooling demand, prices have not experienced a nationwide collapse. The median existing home price in August was $429,100, a 1.6% increase compared to the previous year.
However, this national average masks significant regional variations. The Western United States has seen a price correction of 0.2%, suggesting that markets that became significantly overvalued during the 2021-2023 boom are beginning to see a cooling effect. Conversely, the Northeast, Midwest, and South continue to see price appreciation. This divergence suggests that housing remains highly localized, and for many, the "affordability crisis" is a matter of geography as much as it is a matter of interest rates.
Bess Freedman, CEO of Brown Harris Stevens, highlights the social equity implications of this environment. "We are seeing a bifurcated market," she explained. "Buyers with significant cash reserves are navigating this environment with relative ease, often bypassing the need for financing entirely. First-time homebuyers, however, who are reliant on traditional mortgage products, are finding themselves increasingly marginalized." Currently, first-time buyers represent less than 30% of total home sales, a figure that experts argue is unsustainable for the long-term health of the real estate sector.
A Shift in Leverage: The Rise of Concessions
As the market tilts toward the buyer, the nature of the transaction is changing. With fewer active shoppers, those who remain in the market are exercising greater leverage. Redfin data indicates that in nearly 45% of transactions finalized in the three months leading up to August 2026, sellers provided concessions.
These concessions, which include credits for closing costs, contributions toward temporary interest-rate buydowns, or payments for major repairs, have reached their highest frequency since 2020. This indicates a quiet but significant shift in bargaining power. The era of the "blind bid"—where homes would routinely sell over the asking price within 48 hours—is largely over.
"When borrowing money becomes this expensive, the buyer’s patience for deferred maintenance or inflated list prices evaporates," Johnson observed. "Sellers are having to learn that the market of 2026 is fundamentally different from the market of 2023."
Strategic Evolution in Pricing
Market participants are also witnessing a change in how properties are brought to market. Benjamin Schieken, founder of Fincast, notes that the "strategic evolution" of listing prices is becoming more sophisticated. Previously, sellers might have listed a home at an aggressive price point, hoping to catch a wave of desperate buyers. Today, the strategy is increasingly centered on "pricing to move."
"Sellers are beginning to realize that if they price too high, the house will sit," Schieken said. "We are seeing a trend where sellers are listing at more realistic, or even slightly lower, price points in the hopes of creating a competitive bidding environment that drives the price up naturally. It is a more clinical, data-driven approach to an unpredictable market."
Long-Term Implications for the Economy
The implications of sustained 7% mortgage rates extend beyond individual household budgets. A stagnant housing market ripples through the broader economy, affecting sectors ranging from residential construction and retail furniture sales to title insurance and mortgage banking.
Furthermore, if homeownership becomes a luxury rather than a standard middle-class milestone, the long-term wealth gap in the United States is likely to widen. As the Federal Reserve continues to navigate the path between cooling inflation and avoiding a recession, the housing market serves as a primary stress test. If rates remain at current levels for an extended period, the structural changes observed in 2026 may define the real estate landscape for the remainder of the decade.
For now, the industry remains in a holding pattern. Buyers are waiting for rates to fall or prices to drop; sellers are waiting for a return to historical transaction volumes; and the Federal Reserve is waiting for inflation data to justify a pivot. Until those interests align, the American dream of homeownership will likely remain a deferred ambition for millions.