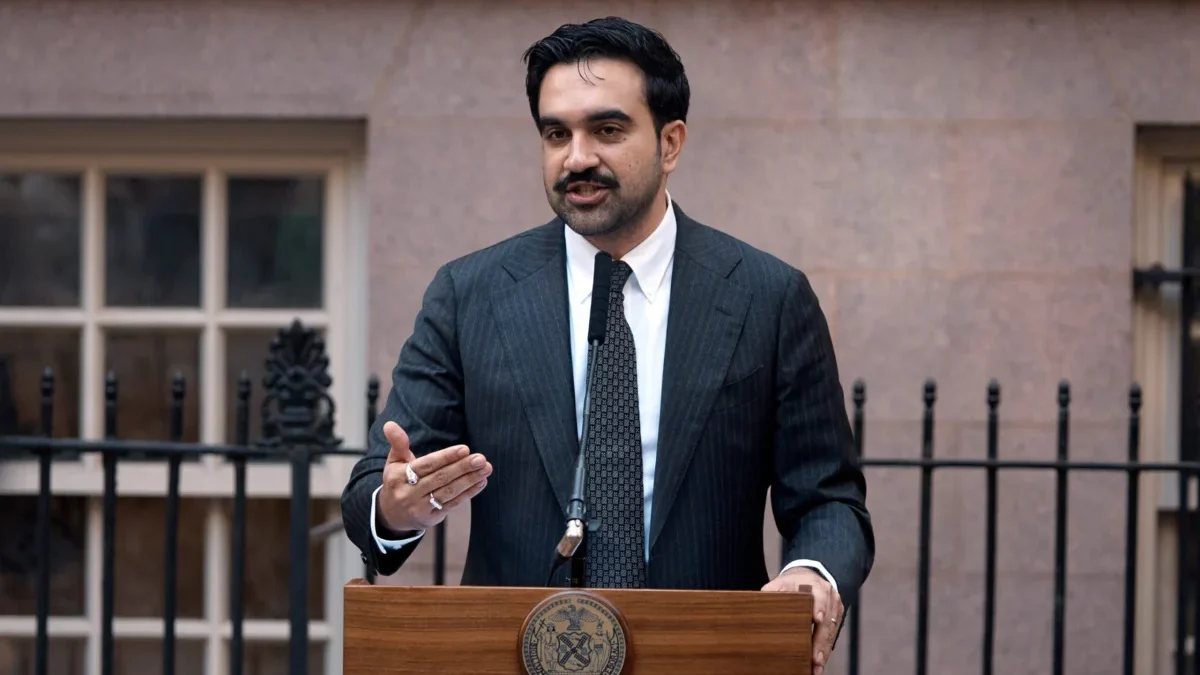
A unanimous ruling from a four-judge panel at the Appellate Division, Second Department, has delivered a significant victory to Mayor Zohran Mamdani’s administration, effectively clearing the path for the continued implementation of the city’s controversial pied-à-terre tax. The court’s decision on Wednesday reversed an earlier judgment by Staten Island Supreme Court Justice Wayne Ozzi, which had previously granted homeowners injunctive and declaratory relief against the Department of Finance (DOF). The appellate court’s swift dismissal—issued just one week after oral arguments—centered on the technical but critical issue of legal standing, finding that the petitioners failed to demonstrate a concrete, individualized injury resulting from the city’s tax assessment methodology.
This litigation represents only one front in a broader, high-stakes battle over the taxation of luxury second homes in New York City. The tax, a centerpiece of Mayor Mamdani’s fiscal platform, targets properties valued at over $5 million that serve as secondary residences. While the administration views the measure as a vital mechanism for wealth redistribution and public investment, critics, including high-net-worth individuals and legal advocacy groups, have consistently challenged the administrative execution of the policy.
The Genesis of the Dispute
The legal challenge, brought forth in August by a group of seven homeowners represented by former First Deputy Mayor Randy Mastro, focused on the Department of Finance’s administrative procedures. The core of the complaint centered on the city’s decision to publish a supplemental roll containing approximately 900,000 properties and the subsequent issuance of roughly 17,000 notices to property owners.
The plaintiffs argued that the DOF’s methodology was fundamentally flawed, alleging that the city effectively shifted the burden of proof onto taxpayers by requiring them to demonstrate their primary residence status rather than utilizing existing municipal or state tax records. The petitioners contended that this "guilty until proven innocent" approach caused undue administrative burden and potential reputational harm.
However, the Appellate Division declined to reach the merits of these procedural arguments, finding the threshold issue of "standing" dispositive. The court emphasized that the mere receipt of a notice or inclusion on a supplemental list did not constitute a legally cognizable injury. The panel characterized the notices as serving an "informational purpose," drawing a parallel to standard debt collection notifications. Furthermore, the court noted that the state legislature, in drafting the enabling legislation, must have reasonably anticipated that the initial notification list would be imprecise, thereby necessitating the very exemption process that the plaintiffs were contesting.
Chronology of the Pied-à-Terre Initiative
The trajectory of the pied-à-terre tax has been marked by rapid policy implementation and immediate pushback:
- Initial Proposal: Mayor Mamdani introduced the tax as a means to capture revenue from non-resident luxury property owners, with initial estimates suggesting an annual windfall of up to $500 million.
- Late 2025/Early 2026: The Department of Finance began the logistical task of identifying properties subject to the surcharge.
- August 2026: The lawsuit led by Randy Mastro was filed, temporarily clouding the implementation process.
- August 12, 2026: The city received updated 2025 state income-tax data, prompting the DOF to refine its target list and clear 1,210 owners of the tax liability.
- Late 2026: The Appellate Division hears arguments regarding the legitimacy of the notification process.
- Present: The court dismisses the challenge, reinforcing the city’s authority to manage the roll-out process.
Economic Implications and Administrative Adjustments
The economic stakes of the pied-à-terre tax are substantial. Comptroller Mark Levine had previously estimated that the tax could generate approximately $380 million from roughly 11,200 properties, while the Mayor’s Office has maintained a more optimistic projection of $500 million annually.
The city’s administrative approach has remained fluid. Following the influx of protest data, the Department of Finance has demonstrated a willingness to pivot. By late summer 2026, the DOF had granted over 8,800 exemption requests, suggesting that the "exemption process" criticized by plaintiffs is functioning, albeit perhaps with a high administrative friction coefficient. The city’s transition from a broad initial notification to a more targeted approach—leveraging the August 2026 receipt of state income-tax data—has arguably mitigated some of the concerns regarding the accuracy of the tax rolls.
The court’s ruling also dismissed arguments that the confusion surrounding the rollout was "generalized, tenuous, and ephemeral." In a pointed observation, the judges noted that the plaintiffs failed to provide evidence of actual damages, such as instances of fraud, stalking, or unauthorized data usage resulting from the public nature of the assessment rolls. Furthermore, the court underscored that the existing annual assessment rolls already contain sensitive data, including owner names and market valuations, rendering the new notifications legally redundant in terms of potential exposure.
Official Reactions and Political Fallout
Mayor Mamdani framed the appellate victory as a triumph for fiscal equity. In an official statement, the Mayor characterized the plaintiffs’ efforts as an attempt by the "ultrawealthy to avoid paying their fair share." He reiterated the administration’s stance that ownership of a secondary home valued in excess of $5 million carries an inherent social responsibility to the city.
"We will implement the pied-à-terre surcharge fairly and efficiently," the Mayor stated, while also signaling that the administration remains prepared for further litigation. The Mayor specifically noted that the city is bracing for "ongoing challenges in Suffolk County," which he attributed to the same interests that faced defeat in the Appellate Division this week.
From the perspective of the plaintiffs, the ruling is a significant setback. By failing to establish standing, the homeowners have been denied the opportunity to argue the merits of their procedural claims before the court. While the panel did offer minor concessions—specifically rejecting the city’s claims of mootness and the argument that tax challenges must be exclusively funneled through the city’s Tax Commission—these points were insufficient to prevent the dismissal of the petition.
Broader Implications for New York Tax Law
The appellate court’s decision provides a degree of clarity for the city’s Department of Finance, effectively validating the agency’s broad discretion in identifying potential tax targets. By establishing that the receipt of an informational notice does not constitute an "injury" in the context of tax administration, the court has narrowed the avenues available for future litigation against similar municipal initiatives.
However, the legal landscape remains complex. With at least three separate legal challenges currently pending against the surcharge, the tax remains in a state of administrative flux. Observers note that while the city has secured a major procedural win, the long-term success of the tax will depend on the DOF’s ability to minimize administrative errors. The "exemption process" will likely become the primary battlefield for future disputes; as more owners seek to prove their residency, the city will face increasing pressure to ensure that its verification methods are both transparent and accurate.
For the real estate market, the tax represents a shift in the cost of ownership for luxury properties. Whether this surcharge will significantly impact property values or deter future investments in the city’s high-end sector remains a subject of ongoing debate among economists. Some analysts suggest that the tax, while politically popular, could potentially depress transaction volumes in the ultra-luxury tier. Conversely, proponents argue that the revenue generated will provide critical funding for public infrastructure and social programs, thereby enhancing the city’s overall desirability.
Ultimately, the court’s decision on Wednesday serves as a reminder of the deference typically afforded to municipal agencies in the administration of tax policy. As New York City continues to navigate the complexities of wealth-based taxation, the interplay between the Mayor’s policy objectives and the legal protections afforded to property owners will continue to shape the city’s fiscal and political future. For now, the Mamdani administration has cleared its most immediate legal hurdle, ensuring that the wheels of the pied-à-terre tax continue to turn.